Get in touch
Download Brochure
Download Guide
Get in touch
NASHVILLE HAS LANDED
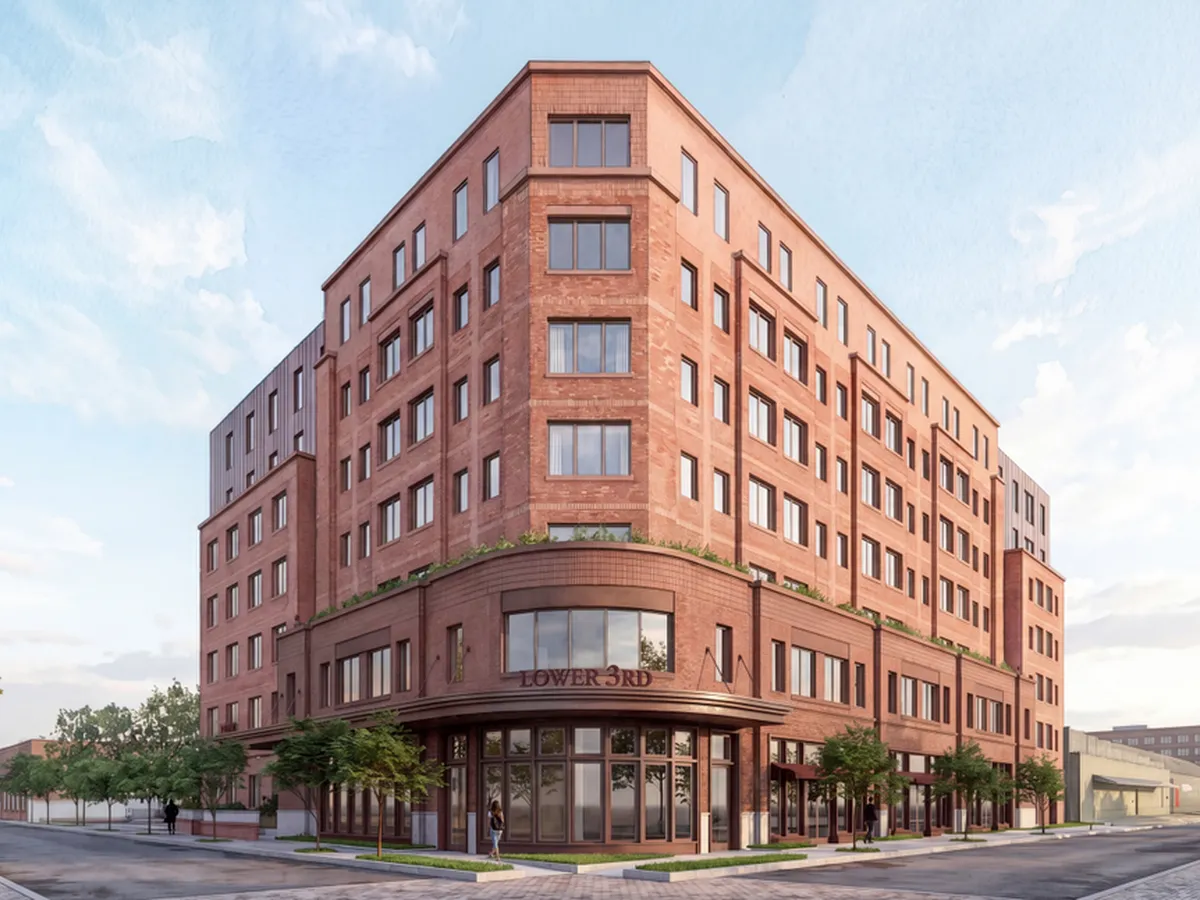
Introducing Cam on Third
Invest in one of America’s fastest-growing cities, with studios, 1 & 2-bedroom apartments from $299,950.
Rightmove House Price Index September 2026: What It Means for Property Investors
The autumn bounce is real, but context matters. September's Rightmove House Price Index brings the first piece of good news in a few months, with asking prices rising 0.7% to £367,440 - the first monthly increase since May.
The traditional autumn bounce, as buyers return from the summer holidays and refocus on moving plans, is beginning to take shape. It’s an encouraging signal, particularly after a summer defined by falling prices, high stock levels and subdued activity, but it needs to be kept in perspective.
What this month's data does confirm is that activity is returning - sales agreed are picking up, and buyer enquiries are rising. Whether that builds into something more sustained through the rest of the year will depend on mortgage rates and wider economic conditions, but the direction of travel so far is more positive than it has been for some time.
The regional divide is the real story
The national headline only tells part of the story as underneath it, there is a striking regional divide which has significant implications for where investors should be focused.
In London, only 42% of homes coming to market are successfully finding a buyer, whereas in the North West, that figure is 71%. That’s not a marginal difference, and points to two fundamentally different markets. This reflects something we’ve been seeing on the ground for some time.
Demand across Manchester and Liverpool remains strong, underpinned by affordability levels and rental demand that continues to support long-term returns. When nearly six in ten London homes are failing to find a buyer, and over seven in ten North West homes are succeeding, the data is telling investors something important about where the fundamentals are strongest.
For investors focused on sustainable yield and long-term returns, the regional picture has rarely been clearer.
Rising mortgage rates mean the numbers need to work from day one
The average two-year fixed mortgage rate has risen again, now sitting at 5.29% - up from 5.09% last month, and significantly higher than the 4.25% seen before the Iran conflict began to drive rates upward. With no clear sign of that reversing in the near term, borrowing costs remain a central factor in what works as an investment.
At this level, there’s no room for weak deals. Investments that rely on future price growth to make the numbers work are increasingly difficult to justify, so what matters is whether the income case, such as the yield, rental demand, and purchase price stack up from the outset.
We’ve also seen a clear shift in how investors are approaching deals as a result. The focus has moved firmly towards markets where rents are realistic relative to local wages, where demand is structural, rather than cyclical, and where the numbers make sense today rather than in five years' time.
What the current market rewards
September's data is a reminder that the property market is really a collection of very different local markets, each with their own supply and demand dynamics, affordability levels, and investment cases.
The current environment is one that rewards investors who are selective, who understand the fundamentals, and who are prepared to negotiate. The margin for error is smaller than it was in the years of rapid price growth, but for those who know where to look, the quality of opportunity remains strong.
Similar posts you may like