Get in touch
Download Brochure
Download Guide
Get in touch
Are Micro-Markets the New Reality of Property Investment?
At Elite, we often see huge variety in investment opportunities in very close locations. For example, two postcodes can be four miles apart in the same city, yet one yields 2.6%, while the other 8.1%.
That gap is something investments must pay attention to. And exactly why we should stop thinking of cities as a single investment market, and start thinking of them as collections of micro-markets, each with its own demand drivers and tenant profile.
As an investor who isn’t asking for the granular yield details within a city, you're leaving return on the table. Successful investors are already asking us which postcode, rather than which city, offers the best return on investments.
City narratives aren't nuanced enough anymore
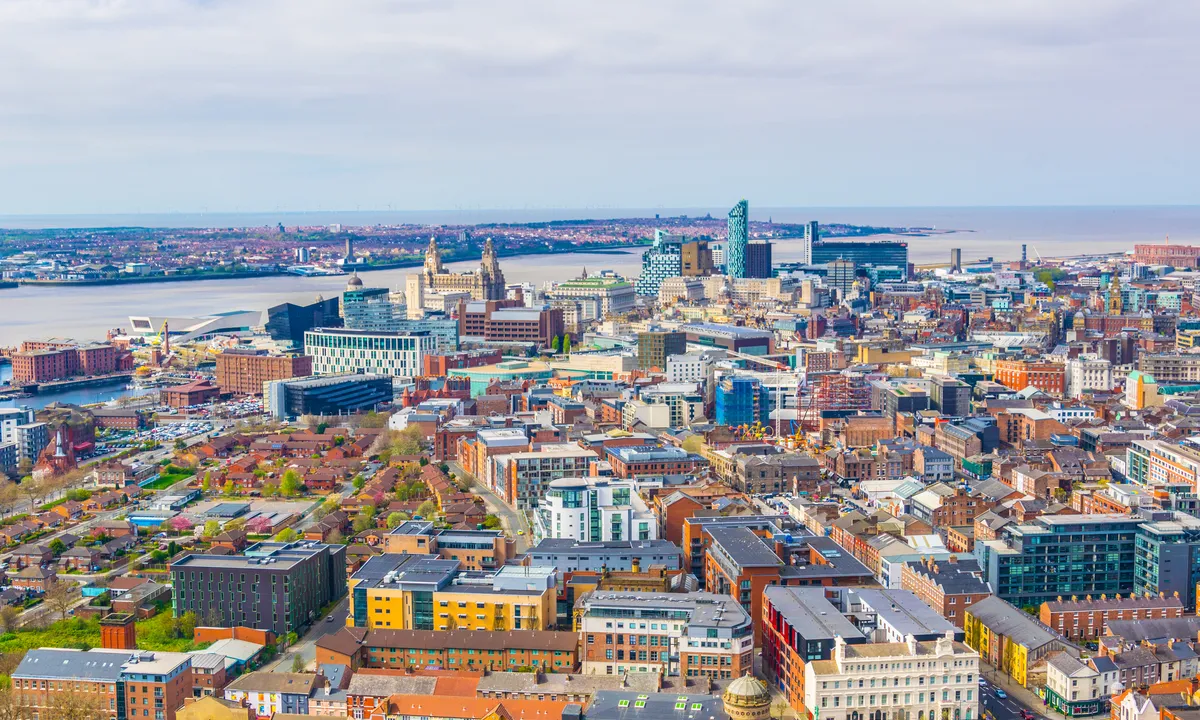
The case for investing in Northern cities has never been stronger. Liverpool, Manchester and Leeds have spent the last decade building genuine investment credentials, thanks to regeneration pipelines, growing graduate populations, employment opportunities and rental demand that keeps outpacing supply.
The data also backs this up. Across 154 UK locations tracked by Property Investments UK, Leeds is currently recording gross yields of 9.6%, against a national average of 5.8%.
But city level thinking only tells part of the story, and increasingly, it's not enough on its own. If you want the best results, you need to go a level deeper, and that's exactly the shift we're seeing play out across our own portfolio as people get more considerate about yield disparities within cities.
Looking closer at the numbers
Once you break the picture down by postcode, the variation is striking. Liverpool alone offers 21 postcode districts, and yields are not spread evenly. The pockets pushing closest to 10% tend to sit around Edge Hill and Kensington, close to the Royal Liverpool University Hospital.
Leeds shows a similar pattern. LS1 and LS2, the city centre postcodes, typically deliver between 5% and 6.5%. Head slightly further out to LS9, covering areas like Cross Green and Richmond Hill, and yields climb to 8% to 10% for investors who know where to look.
Manchester follows a similar pattern. The city-wide yield average sits around 6% to 7%, but the Northern Quarter regularly reaches 9% to 11%, and slightly outer postcodes such as Salford and Stretford consistently outperform the broader market too. These are the kinds of gaps our team look for when assessing a new development to bring to market.
What drives postcode performance?
We’re nearing a decade in business now, and over the years, our team of experts has noted three factors that consistently separate the strongest postcodes from the rest.
Proximity to anchor institutions is the first. Hospitals, universities and large employers generate reliable, recurring demand from tenants who stay, renew and refer, letting landlords protect against void periods that would sink returns elsewhere.
The second is active regeneration backed by committed investment. The sweet spot isn't the postcode that's already arrived, it's the one in the early or mid-stages of a credible programme, where you can buy in ahead of the growth curve. By the time a place is obviously in demand, the yields have already been affected by the increased desirability.
The third, and the one many investors often overlook, is tenant demographic fit. High yields with frequent turnover look identical on a spreadsheet to strong yields underpinned by professional or graduate demand and low void rates.
These are not the same investment, and it’s so imperative to understand that. While one is a number, the other is a resilient asset.
Yield isn't the only number that matters
The postcode-level yields above are compelling, but yield is only one part of the return equation. It’s also vital to consider short-term let optionality, and capital growth.
Where a development carries short-term let (STL) planning permission, you gain genuine flexibility and access to higher nightly rates from professional and corporate short-stay demand in city centre postcodes. This is achieved while keeping the option open to switch back to a standard long-term let if conditions favour stability over yield.
Capital growth is the other factor a yield table alone won't show. Some of the highest-yielding postcodes above are already fully let and already priced in, so the yield is strong today but the scope for further value growth is limited. City centre postcodes anchored by confirmed regeneration often carry lower entry-level gross yields but a clearer path to capital appreciation, particularly once net yield, after service charges and realistic void periods, is properly modelled.
This is why we don't select opportunities on gross yield alone. A postcode offering a slightly lower headline yield but deeper professional tenant demand, STL optionality and a credible regeneration timeline can outperform a higher-yielding postcode once income and capital growth are considered together.
The direction of travel
At Elite, this is the lens through which we evaluate every opportunity for you. We don't simply ask which city, we ask which postcode and why it will generate the returns you're looking for. Our current portfolio is national, and each development has been selected on exactly this kind of analysis.
City level thinking got a lot of investors to the right part of the country. Now, postcode level thinking, or micro-market thinking, is what will deliver a genuinely strong portfolio.
Similar posts you may like